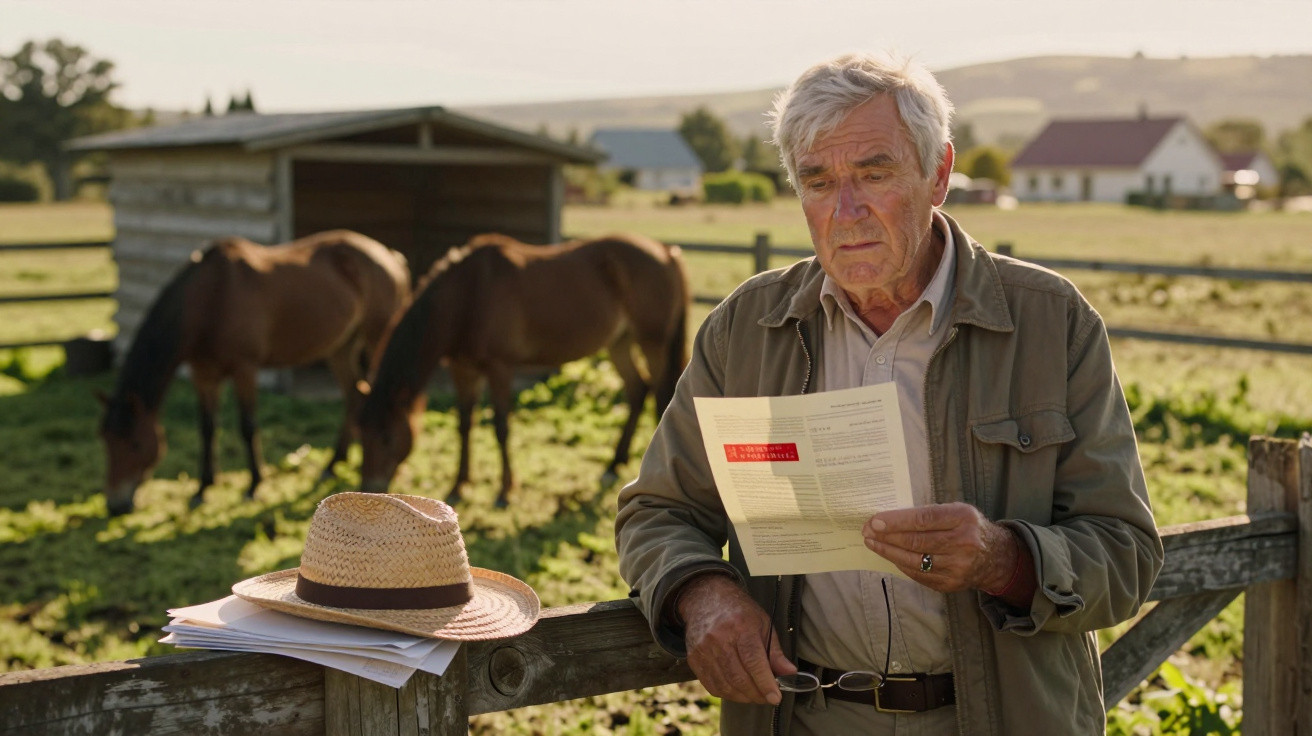
At the edge of the field, a retired factory worker held a mug of tea and watched his cousin pitch hay to a rescued mare whose ribs remained visible beneath her winter coat. It was the sort of unobtrusive, ordinary generosity that never makes it onto social media.
By lunchtime, however, the same pensioner was calling the local tax office. His voice faltered as he tried to work out why offering a few acres to help unwanted horses had resulted in a four-figure agricultural tax bill. There was no business plan and no profit, only a favour for family that had unexpectedly acquired a cost.
His cousin’s parents were unequivocal: kindness does not override the law. The state took the same view.
Somewhere between the rescue horses and the tax authority, the situation ceased to seem straightforward.
“You can’t tax kindness”… or can you?
At first glance, it is almost a familiar story: a retiree on a modest pension, an unused field, and a cousin urgently needing somewhere safe for abused horses that no one else will take. They agree over Sunday lunch with a handshake. There are no solicitors, contracts or formalities, just trust and the shared conviction that doing the right thing ought to be sufficient.
A few months later, that peaceful image meets a letter bearing official blue ink. The tax office states that the land is now “used for agricultural purposes” and must be classified and taxed accordingly. The retiree reads the notice in disbelief, torn between guilt and confusion. In his mind, he had merely helped his cousin.
The law reached another conclusion.
From the cousin’s perspective, the account is very different. She describes horses arriving scarred, hollow-eyed and with neglected hooves left to deteriorate. After working nights, she forces herself up to clean stables that were never intended to be on this quiet patch of family land. There are no sponsorship arrangements or polished charity appeals, only second-hand rugs and discounted feed.
Her parents, who signed some of the documents alongside her, offer a less forgiving assessment: “We warned you,” they say. “Land use is land use. Tax doesn’t care why you’re doing it.” To them, the demand confirms what they had feared all along. In their view, good intentions were never likely to overcome the legal definition of “agricultural activity”.
The sums can seem unreal: hundreds, perhaps thousands, depending on the country and its local rules. It may be enough to cancel a holiday, eat into savings or push an already precarious retirement into overdraft. Nobody is earning money from the arrangement, yet the bill is as tangible as the muck on the cousin’s boots.
In legal terms, the reasoning is harsh but consistent. In many jurisdictions, regular land use for animal husbandry - whether for cattle, goats or horses - is treated as agriculture. Once that threshold is crossed, the land may fall into a different tax band, bring reporting requirements or lose exemptions associated with “non-productive” use. The tax office does not assess motives; it records activity.
That is where the moral tension emerges. The retiree feels penalised for showing compassion. The cousin feels responsible for involving him. Her parents feel both weary and vindicated. Officials maintain that they are applying the rules equally, since making exceptions for sympathetic rescue cases raises the question of where such exceptions would end.
This is the uneasy point at which everyday ethics encounter systems built to disregard emotion. The horses are indifferent to the dispute. They only know that, for now, the field is safer than the places they left behind.
How a simple favour becomes a taxable “operation”
This situation carries a quiet and unglamorous lesson. Before lending land - even to relatives and even for a worthy cause - take one mundane step: set out in writing what the land will be used for and who accepts the legal responsibilities. That is not about suspicion or defensiveness. It is simply a way to avoid unexpected letters later.
A straightforward written agreement can state whether the land remains for “recreational” or “personal use”, or whether it is moving into an “agricultural” or “commercial” classification. It need not resemble a 40-page contract. A signed, dated two-page document may be sufficient for an accountant or local official to conclude, “OK, this is clearly not a business.” In its absence, authorities tend to adopt the interpretation that is safest for them, rather than the one that favours you.
That is precisely how a kind gesture begins to cost money.
At a personal level, it is easy to understand why people avoid the paperwork. Producing documents can feel unfeeling when a cousin is describing animals that might otherwise be shot. You are drinking coffee, not negotiating a corporate tenancy. Around a kitchen table scattered with crumbs and veterinary bills, tax rules are the last thing anybody wants to discuss.
From a policy perspective, land-use rules have been tightened in many jurisdictions. In some areas, tax offices already monitor how long fields remain unused, which animals are kept on them and, in extreme instances, satellite images. A field that suddenly contains paddocks, hay deliveries and informal donations may appear to an algorithm exactly like a small equine operation.
Most of us have seen a “small side project” grow into something far more substantial. Two rescue horses can become six, then ten, followed by a continuing run of “just one more” emergencies. Every generous decision quietly expands the activity’s footprint. When the tax demand finally arrives, the project may already resemble an established yard on paper.
The cruel irony is that, in many countries, formally registering as a non-profit organisation or recognised rescue may reduce part of the tax liability. Yet that route can appear daunting and bureaucratic, so people carry on informally until they encounter a barrier. The retiree in this case never believed he was hosting anything beyond an act of mercy in a field behind his home.
Staying kind without getting crushed by the system
It is possible to protect both your compassion and your finances when offering help. Begin with questions rather than with the number of horses or people you intend to assist. Before lending land, ask three direct questions: “Does this look like agriculture on a map? Will animals live here year-round? Could money change hands because of this field?” Even one yes should prompt a conversation with a tax adviser or local authority.
Another sensible measure is to separate responsibilities. The landowner can remain solely the owner, while the cousin, neighbour or charity becomes the formal “operator”. It is a small distinction, but it may determine who the tax office approaches first. A simple agreement for a nominal rent, or a clause stating “use at own risk and responsibility”, may feel overly formal at a family barbecue, but can prevent prolonged disputes later.
This is not about mistrusting those close to you. It is about understanding how systems interpret arrangements.
A common emotional mistake is to assume that good intentions will “speak for themselves” if trouble arises. They will not. Tax returns and land registers cannot hear accounts of rescue horses or late-night veterinary calls. On a peaceful Sunday, it may be tempting to think, “It’s just family, nothing official.” Later, the thought becomes, “How did this get so complicated?”
In practical terms, the same patterns recur. People misjudge how long supposedly “temporary” use will continue. They fail to retain receipts or evidence showing that the work is a genuine rescue rather than a business. They combine personal bank accounts with donations and then cannot demonstrate that no profit was ever made. And, yes, they treat “kindness” as though it were a legal category.
The human impact can be particularly painful. No one wants to feel foolish for trusting family members. No one wants to acknowledge that they did not read a letter properly six months earlier.
“The taxman isn’t the villain here,” one local accountant told us. “The real problem is when people build entire projects on hope and handshakes, then act surprised when the law doesn’t speak that language.”
Several practical steps can reduce the impact behind the scenes:
- Speak to a tax professional before the first animal or project arrives on the land.
- Create a written land-use agreement, even with relatives, that clearly allocates roles.
- Retain photographs, invoices and records to demonstrate that it is a genuine rescue rather than a disguised business.
- Consider non-profit or charity status if the activity grows beyond a handful of cases.
- Reassess the arrangement annually rather than waiting for a crisis. Let’s be honest: nobody really does that every day.
The quiet price of kindness in a rules-first world
The retired landowner at the centre of this story eventually paid the agricultural tax demand. It was not because he came to agree with it, but because contesting it felt more burdensome than paying. Most mornings, he still walks to the field, rests against the old fence and watches the horses graze as though nothing has happened.
But something has changed. He is more cautious now. When a neighbour recently asked to use a corner of the field for a bee project, his instinctive response was no longer “How can we help?” but “Who’s going to be on the hook if this goes wrong?” That is the unseen harm: every bureaucratic shock makes people hesitate before agreeing to support the next worthwhile cause.
At a wider level, the story presents an uncomfortable question: how should society deal with untidy, generous acts that do not fit neatly within legal categories? Parents telling their daughter that “kindness is no excuse for dodging the law” may sound harsh, but they are also trying to shield her from a world in which systems seldom bend. We can object to that reality, or learn to operate within it by giving informal compassion a little more structure without destroying its spirit.
We have all experienced a moment when a straightforward favour suddenly appears to belong in a spreadsheet. Perhaps the answer is not to let such moments make us entirely hard-hearted. You can continue lending land, time and skills. You can still say yes. Just allow one dull but necessary question to sit beside that yes: “What will this look like on paper, six months from now?” It is neither romantic nor heroic, but it may be what enables generosity to survive.
| Key point | Detail | Why it matters to the reader |
|---|---|---|
| The law considers use, not intention | Any regular use of land for animals may be reclassified as taxable agricultural activity. | Understand why a good deed can lead to a tax assessment. |
| A simple written agreement can change everything | A short document setting out roles and land use can reduce the owner’s risk. | A practical tool for protecting family relationships and personal finances. |
| Give generosity some structure, even minimally | Non-profit status, retained receipts and separate accounts help demonstrate that the activity is not a business. | Keep helping without being overwhelmed by rules and taxes. |
Comments
No comments yet. Be the first to comment!
Leave a Comment